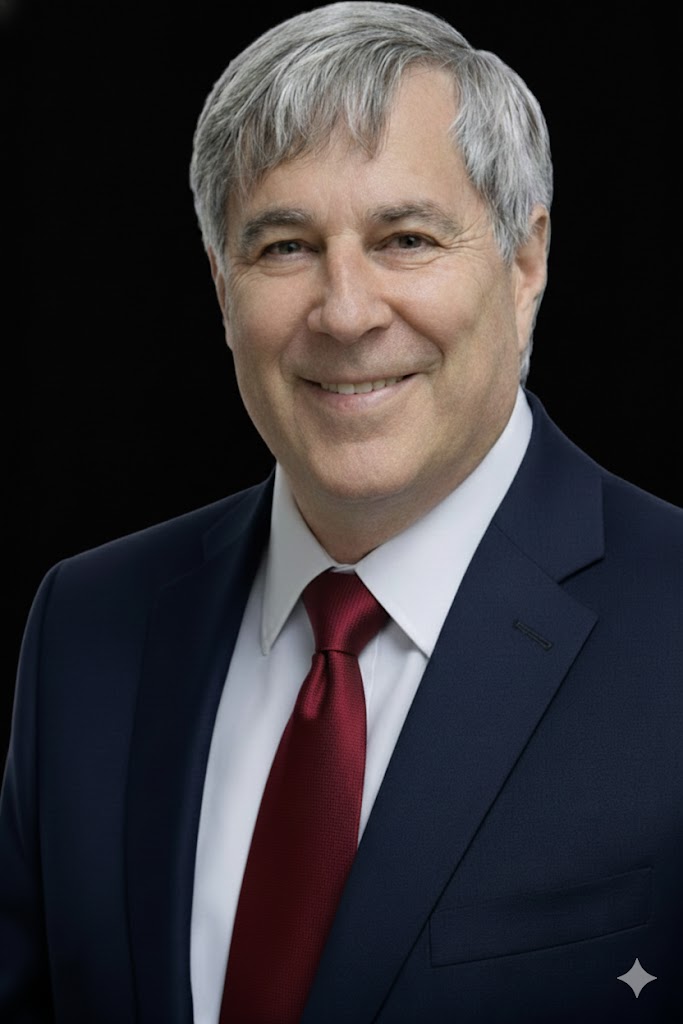
Former SEC Enforcement Attorney · 9 Years, SEC Division of Enforcement
Former SEC Enforcement Attorney

Nine Years InsideSEC Enforcement

Securities counsel for issuers who want filings reviewed the way the SEC staff reviews them.

Frederick M. Lehrer spent nine years in the SEC's Division of Enforcement — three of them concurrently as a Special Assistant U.S. Attorney — and has practiced securities and corporate finance law for more than 25 years, including advising overseas issuers on U.S. securities law.

Frederick M. Lehrer - International Securities Attorney
Frederick M. Lehrer
Attorney & Counselor at Law
9 Yrs
SEC Division of Enforcement
3 Yrs
Special Asst. U.S. Attorney
25+
Years in Private Practice
Flat Fee
Defined Scope, No Hourly Billing
About the Firm

International Securities Attorney
Frederick M. Lehrer

Frederick M. Lehrer advises U.S. and overseas issuers on U.S. securities law and has practiced in securities and corporate finance for more than 25 years. The practice covers going-public disclosures, SEC periodic reports, registration statements, private placement memoranda, mergers and acquisitions, Regulation A offerings, OTCQB and Pink quotations, and exchange listing applications.

Frederick Lehrer's clients have included a wide array of various industries, including entertainment, sports, cannabis, AI, real estate, hydration drinks, shipping, lending, telecommunications, animal nutrition, cryptocurrency, gaming, and electric vehicles.

★★
U.S. Army Veteran — 1967–1969
Army Commendation Medal · Vietnam Service Medal
Served as a Specialist 5. Duty, precision, and accountability under pressure — the foundation of every chapter of his career.
Read More About the Firm
Flat-Fee Monthly Scope

Monthly Securities Law Services

Ongoing work is handled under a monthly flat fee with a scope set in writing. No hourly billing and no separate charge for client calls within that scope.

SEC filings and disclosure (10-Q, 10-K, 8-K, Form D)
Press release and investor deck disclosure review
Agreement review (service, investment banking, securities purchase)
Corporate governance questions
Ongoing compliance support

Registration statements, private placement memoranda, and other large drafting projects are quoted separately on a flat-fee basis.

Schedule a Consultation
Securities Offerings

Capital Raising & Offering Compliance

When raising capital through public or private offerings, compliance with securities laws is critical to avoid severe penalties. Mr. Lehrer assists businesses with preparing and filing the necessary documentation and disclosure required by the SEC. These services are offered on a flat-fee basis with negotiated installment payments.

Why Choose Frederick M. Lehrer?

Quality Legal Solutions, Tailored for You

Finance-Oriented Mindset
Attorney Lehrer understands the financial challenges his clients face. He offers affordable, flat monthly securities law fee and registration statement fee arrangements to ensure high-quality representation without unexpected costs.
Hands-On Approach
From your initial consultation to resolution, Attorney Lehrer is directly involved in every step of your securities law matters, helping you explore all potential legal options.
25+ Years of Experience
More than twenty-five years of securities and corporate practice, applied to complex disclosure, offering, and transactional matters.
Your Partner in Corporate Finance
Frederick M. Lehrer is your trusted partner in corporate financial matters, providing strategic advice including structuring deals, navigating negotiations, and mitigating risks.
Transparent Pricing

Flat Fee Arrangements with a Defined Scope

Ongoing securities work is billed as a monthly flat fee against a written scope of services. Larger projects — a registration statement or private placement memorandum, for example — are quoted separately, also on a flat-fee basis.

No hourly rates
Scope agreed in writing before work begins
Calls and questions within scope carry no separate charge
No referral fees to other law firms
Schedule a Consultation

"Attorney Lehrer is directly involved in every step of your securities law matters, helping you explore all potential legal options."

— Frederick M. Lehrer, P.A.
Client Testimonials

Trusted by Executives & Public Companies

5.0out of 5
Based on 4 client reviews
5
4
4
0
3
0

“A rare combination of speed, precision, and strategic judgment—Frederick M. Lehrer is our counsel for securities and transactional work.”

C
CEO, Public Company
Public Company Client

“A thoughtful advisor in complex transactions. His SEC disclosure work is detailed, and the turnaround has consistently met our deadlines.”

C
CFO, Publicly Traded Corporation
Public Company Client

“When timing and accuracy matter, he delivers—his command of SEC regulations and transactional detail is a real advantage for us.”

GC
General Counsel
Public Company Client

“For nearly a decade, we've relied on Frederick M. Lehrer for corporate securities and regulatory compliance work, accurate turnaround, and a steady hand on high-value corporate finance matters.”

MD
Managing Director
Long-Term Client

Comments from clients of the firm, used with permission. Each matter is different; prior results do not guarantee a similar outcome in any other matter.

Schedule a Consultation
The Book

The Other Side of the Table

Fred's book on what nine years of SEC enforcement teach issuers about disclosure, capital, and going public.

See the Book
The Podcast

Inside Securities Law with Frederick M. Lehrer

Perspective from inside the SEC — translated for issuers, boards, and counsel.

All Episodes
EP 25September 18, 2026 · 3:04

Regulation A-Plus: What the Mini-IPO Actually Costs You

Regulation A-plus gets described as a mini-IPO. That is fair shorthand, and like most shorthand it leaves out the part that matters. Here is the structure. Regulation A has two tiers. Tier 1 permits up to twenty million dollars in a twelve-month period. Tier 2 permits up to seventy-five million. You register on Form 1-A, and unlike an S-1, you may test the waters — you can solicit indications of interest before you file, provided those materials are filed with the Commission. The advantages are real. Tier 2 preempts state Blue Sky registration for sales to qualified purchasers, which removes a substantial layer of cost. Financial statement requirements are lighter than an S-1. And the offering can be sold directly to retail investors. Now the part that gets left out. Form 1-A is qualified by the SEC staff. It is not automatic. The staff comments on it, and in my experience those comments land in the same places they land on an S-1: the business description, the use of proceeds, and the risk factors. Companies that treat Form 1-A as a lighter document tend to draw more comment rounds, not fewer. Tier 2 carries ongoing reporting. An annual report on Form 1-K, a semiannual report on Form 1-SA, and current reports on Form 1-U. That is lighter than the Exchange Act calendar, but it is not nothing, and a company that stops filing loses the exemption for future offerings. Tier 2 also caps what non-accredited investors may put in — generally ten percent of the greater of their annual income or net worth. If your offering depends on large retail checks, that cap constrains you. And Regulation A-plus does not create a trading market. Qualification lets you sell shares. It does not give you a ticker symbol. If you want your shares quoted, that is a separate process involving a market maker and a filing with FINRA. So who is Regulation A-plus actually right for? A company with a genuine retail following, a defined use of proceeds, and the ability to carry semiannual reporting. Consumer brands do well with it. Companies with a complicated capital structure and no natural audience generally do not. I handle Form 1-A drafting and the qualification process on a flat fee, because the scope of that work is definable in advance and the cost should be knowable before it begins. This is Inside Securities Law. I'm Frederick M. Lehrer. General information, not legal advice.

Listen
EP 22September 16, 2026 · 3:14

The Five Roads to Public Company Status

There is no single way to become a public company. There are five, and choosing the wrong one costs a company a year and a great deal of money. The first is the traditional IPO on Form S-1. You register an offering with the SEC, an underwriter markets it, and shares are sold to the public. It is the slowest road and the most expensive, and for most companies it requires an underwriter willing to take the deal. The second is Form 10. Form 10 registers a class of securities, not an offering. You are not raising money. You are electing to become a reporting company, and sixty days after you file, the registration becomes effective whether or not the staff has finished commenting. Companies use this when they want reporting status first and a market later. The third is Regulation A-plus, sometimes called a mini-IPO. Tier 2 lets you raise up to seventy-five million dollars in a twelve-month period on Form 1-A. The disclosure obligation is real, but the ongoing reporting is lighter than the Exchange Act calendar. The fourth is a direct public offering. You register on Form S-1 and sell the shares yourself, without an underwriter. It costs less. It also means you are responsible for finding every investor. The fifth is a reverse merger. You merge into an existing public shell and inherit its reporting status. It is the fastest road and it carries the most inherited risk. I will spend a whole episode on that one. So how do you choose? Three questions. First: do you need capital now, or do you need public status now? If you need capital, you are looking at an S-1, Regulation A-plus, or a DPO. If you need status, Form 10 or a reverse merger. Second: are your financial statements audited and current? Every road requires audited financials. Stale audits are the single most common reason a going-public timeline slips. Third: how much ongoing reporting can you actually sustain? An S-1 that goes effective puts you into 10-K, 10-Q, and 8-K obligations permanently. Regulation A-plus Tier 2 requires semiannual reporting instead. That difference matters more to a small company than most founders expect at the outset. I spent nine years in the SEC's Division of Enforcement and three decades in private practice, and the pattern is consistent. The road gets chosen for speed. The reporting burden gets discovered afterward. Pick the road that matches the obligations you can carry. This is Inside Securities Law. I'm Frederick M. Lehrer. This episode is general information, not legal advice.

Listen
EP 20September 10, 2026 · 3:13

Reverse Mergers: Speed, and the Shell You Inherit

A reverse merger is the fastest way to become a public company. The reason it is fast is that someone else already did the work. That is also the reason it is risky. The structure is simple. A private operating company merges into a public shell. The shell's shareholders end up with a minority position, the private company's owners end up with control, and the combined entity is a reporting company from day one. No S-1. No underwriter. No waiting for effectiveness. Then you file what practitioners call a Super 8-K, generally within four business days, containing essentially all the information a Form 10 would have required. Audited financials of the operating company. Full business description. Risk factors. Management. Related-party transactions. The disclosure obligation does not disappear. It moves. Here is what I tell every client considering this. You are not buying a corporate structure. You are buying a history. Every liability that shell ever incurred — every lawsuit, every unpaid tax, every undisclosed agreement, every stock issuance that may not have had a valid exemption — you are acquiring all of it. Shell diligence is the entire transaction. If the diligence is thin, the deal is a liability transfer with a ticker attached. Second, former shell status follows the company. Rule 144 is generally unavailable for securities of a company that was ever a shell, unless the company has ceased to be a shell, is current in its reporting, has filed the information a Form 10 would require, and twelve months have passed since that filing. In practical terms, your shareholders' stock is locked up longer than they expect, and they will be unhappy about it. Third, the shareholder base. Shells often carry a scattered group of holders left over from prior promotions. You have no relationship with those people and no control over what they do with their shares once a market appears. Fourth, the staff knows the pattern. Reverse mergers into dormant shells have been the vehicle for a great many pump-and-dump schemes. That does not make your transaction improper. It does mean your filing will be read closely. A reverse merger into a clean, well-documented, reporting shell, with real diligence and honest disclosure, is a legitimate and sensible transaction. I have handled them. The failures I have seen almost always trace back to diligence that got skipped because the seller was in a hurry. Be the party that is not in a hurry. This is Inside Securities Law. I'm Frederick M. Lehrer. General information, not legal advice.

Listen
The Firm's Perspective

What Twenty-Five Years of Securities Practice

Actually Looks Like

"Most securities attorneys read the regulations. I spent nine years enforcing them. When I review a client's S-1 or Regulation D offering, I am not consulting a checklist — I am running the same analytical framework I used at the SEC's Southeast Regional Office to evaluate whether a filing would attract scrutiny, generate a comment letter, or escalate into a formal investigation."

— Frederick M. Lehrer, Former SEC Enforcement Attorney

The Enforcement Background That Changes the Advice

From 1991 through 2000, Frederick M. Lehrer served as an attorney in the Division of Enforcement at the U.S. Securities and Exchange Commission's Southeast Regional Office. During those nine years, he participated in investigations involving insider trading, accounting fraud, market manipulation, misleading disclosures, and failures to file required reports under federal securities law. He was not a compliance officer reviewing policies — he was building cases.

From 1997 through 1999, he served concurrently as a Special Assistant United States Attorney in the Southern District of Florida, prosecuting securities-related financial crimes. That dual civil-and-criminal enforcement experience — understanding both how the SEC builds a civil enforcement action and how the DOJ constructs a criminal prosecution — is not something that can be acquired from a textbook or a continuing legal education seminar.

When that background is applied to private practice, the result is advisory work that is fundamentally different from what a securities attorney without enforcement experience can offer. The firm evaluates every disclosure, every registration statement, and every investor communication from the perspective of how the SEC staff would analyze it — because that is exactly how the firm's principal was trained to analyze documents.

Issuer-Side Representation: What the Practice Actually Covers

The firm's practice focuses on issuer-side representation. This means the firm represents companies — not investors, not regulators, not plaintiffs' class action counsel. The firm's clients are issuers preparing to access public capital markets, companies managing ongoing disclosure obligations under the Securities Act of 1933 and the Securities Exchange Act of 1934, and private companies conducting capital raises through exempt offerings under Regulation D.

Engagements typically involve preparing and reviewing SEC filings — Forms 10-K, 10-Q, and 8-K — drafting and revising registration statements such as Form S-1 and Form 10, advising on Regulation A offerings, and assisting companies conducting capital raises through Regulation D private placements. Many clients are companies preparing to go public or transitioning from private capital raising into public market reporting obligations.

Others are established reporting companies requiring ongoing securities counsel to review disclosures, evaluate investor communications, and address SEC comment letters. The firm also advises companies operating in industries subject to heightened regulatory scrutiny — cannabis and CBD companies navigating federal illegality disclosures, artificial intelligence companies describing rapidly evolving technologies to investors, and cryptocurrency or digital asset issuers evaluating whether a token or digital instrument may constitute a security under the Howey test.

On Disclosure Precision

Why Boilerplate Risk Factors Are No Longer Sufficient

In industries subject to heightened regulatory scrutiny, disclosure precision is critical. Boilerplate risk factors — the kind that say "we operate in a heavily regulated industry and changes in law could adversely affect our business" — are often insufficient when regulators expect detailed explanations of operational risk, legal uncertainty, and compliance frameworks.

A cannabis company that discloses federal illegality in a single generic paragraph is not adequately disclosing the specific operational risks that flow from that illegality — banking access, interstate commerce limitations, Schedule I classification implications for employees, and the risk that federal enforcement priorities could shift. An artificial intelligence company that describes its technology in aspirational terms without disclosing the specific risks of model failure, regulatory classification, or data privacy liability is creating exactly the kind of disclosure gap that generates SEC comment letters.

The firm's approach to disclosure review is shaped by enforcement experience. When reviewing registration statements, periodic reports, or investor communications, filings are evaluated from the perspective of how the SEC staff might analyze the document. This perspective allows potential disclosure deficiencies to be addressed before they become the subject of regulatory inquiries or comment letters — and long before they become the basis for an enforcement action.

1984 – 2000

U.S. Securities and Exchange Commission

Sixteen years at the Commission — first as an investigator, then nine years as an enforcement attorney in the Southeast Regional Office — working insider trading, accounting fraud, market manipulation, misleading disclosures, and reporting failures. Built cases. Evaluated filings. Understood how enforcement actions begin.

1997 – 1999

Special Assistant U.S. Attorney

Concurrent appointment in the Southern District of Florida prosecuting securities-related financial crimes. The dual civil-and-criminal enforcement perspective — understanding both how the SEC builds a civil action and how the DOJ constructs a criminal prosecution — is the foundation of the firm's risk analysis today.

2000 – Present

Private Practice

More than twenty-five years advising issuers worldwide on SEC registration, disclosure obligations, Regulation D private placements, Regulation A offerings, going public transactions, and ongoing reporting compliance. Flat-fee structure designed to remove the hesitation companies feel when seeking early legal guidance.

Flat-Fee Structure

Compliance Support Model

This firm utilizes a flat-fee structure for both ongoing compliance advisory and specific project-based engagements. This approach is designed to provide clients with predictable legal costs, allowing for a defined budgetary framework when managing regulatory requirements.

By utilizing a fixed-fee model, the firm aims to facilitate an environment where communication regarding securities guidance is frequent and proactive. This structure is intended to support the primary goal shared by both the firm and the client: the production of accurate, complete, and defensible disclosures.

Industries the Firm Regularly Advises

The firm's clients span a wide range of industries, including entertainment, sports, cannabis and CBD, artificial intelligence, real estate, hydration and consumer products, shipping, lending, telecommunications, animal nutrition, cryptocurrency and digital assets, gaming, and electric vehicles. What these industries share is not their business model — it is their need for securities counsel who understands how their specific operational characteristics translate into disclosure obligations, and how those disclosures will be evaluated by the SEC staff.

Cannabis & CBD
Artificial Intelligence
Cryptocurrency & Digital Assets
Electric Vehicles
Real Estate
Entertainment & Sports
Telecommunications
Financial Services

The firm is based in Florida and serves clients internationally. Consultations are confidential and available by phone, video, or in person.

Frequently Asked Questions

Common Questions About

Securities Law & Our Services

Ongoing securities work is handled under a monthly flat fee covering a defined scope: SEC periodic filings (10-K, 10-Q, 8-K, Form D), disclosure and press-release review, agreement review, and governance questions. Registration statements, private placement memoranda, and other large drafting projects are quoted separately on a flat-fee basis. No hourly billing, and the scope is set in writing before work begins.

Before entering private practice, Mr. Lehrer spent nine years as an enforcement attorney in the SEC's Division of Enforcement, investigating and prosecuting fraudulent schemes and other violations of federal securities laws. During three of those years he served concurrently as a Special Assistant United States Attorney in the Southern District of Florida.

Yes. Frederick M. Lehrer, Attorney and Counselor at Law, is a national and international law practice that focuses on securities and corporate law matters. He serves clients worldwide from his office in Clermont, Florida, handling cross-border offerings, foreign private issuers, and international compliance matters.

Frederick M. Lehrer offers comprehensive securities law services including SEC disclosure and reporting, SEC registration statements, going public matters, private placement memoranda, OTC market filings, proxy statements, insider reports, private exemptions, Blue Sky compliance, investor relations compliance, and Rule 506 compliance.

Frederick M. Lehrer assists companies in going public through multiple paths including traditional IPOs (Form S-1), Regulation A+ offerings, direct public offerings, reverse mergers, and OTC market listings. He handles all SEC filings, FINRA applications, and Blue Sky compliance from start to finish.

Frederick M. Lehrer offers flat-fee arrangements for most securities law services, providing transparent, predictable pricing. Clients pay a monthly flat fee for ongoing legal services, with registration statements and large document preparation also offered on a flat fee basis — making budgeting straightforward for startups and established companies alike.

Frederick M. Lehrer spent nine years as an enforcement attorney in the SEC's Division of Enforcement, where he investigated and prosecuted fraudulent schemes and violations of federal securities laws. During three of those years he served concurrently as a Special Assistant United States Attorney in the Southern District of Florida, giving him unique insight into how regulators think and act.

Have a question not listed here? Contact us for a free consultation.

Ask Frederick M. Lehrer
Email Fred Directly(561) 706-7646